When Airbnb (ABNB) is outperforming, Brian Chesky is not subtle about it. He opened Thursday’s call with:
“When you look back at our results, over the last several quarters, there is a clear story emerging: Airbnb is back in growth mode. It’s rare for a marketplace of our size to reaccelerate growth, but that’s exactly what we’re doing.”
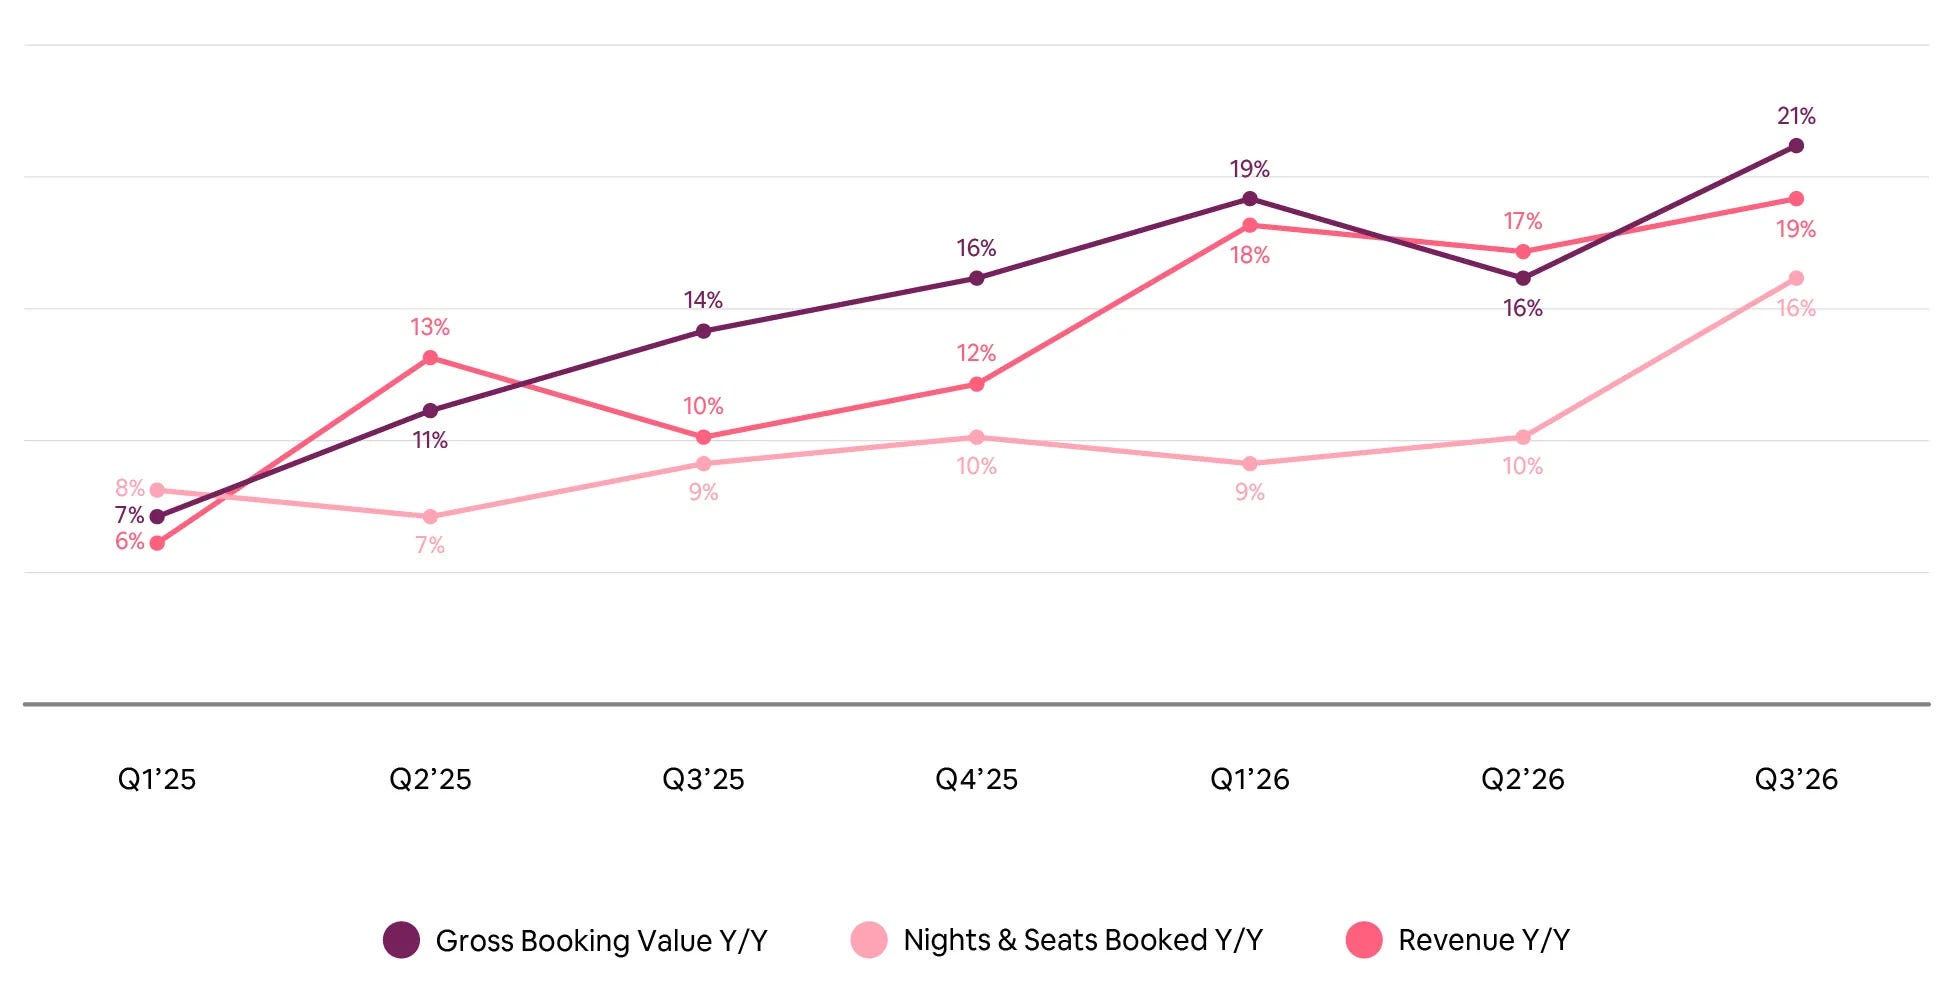
For those who missed it, Aquitaine’s May deep dive argued (emphatically) that Airbnb’s growth would accelerate well above consensus expectations.
The thesis first appeared in a November 2025 preview, when Airbnb was ~$117 and Aquitaine’s second-largest holding at roughly 25% of the portfolio. The position later exceeded 50%, a direct result of Chesky’s off-script remarks on The Information’s TITV in January. Those remarks implied that consensus revenue forecasts were several billion dollars too low.
Unlike management’s earlier commentary on the new businesses, those remarks came without qualifiers or walk-backs:
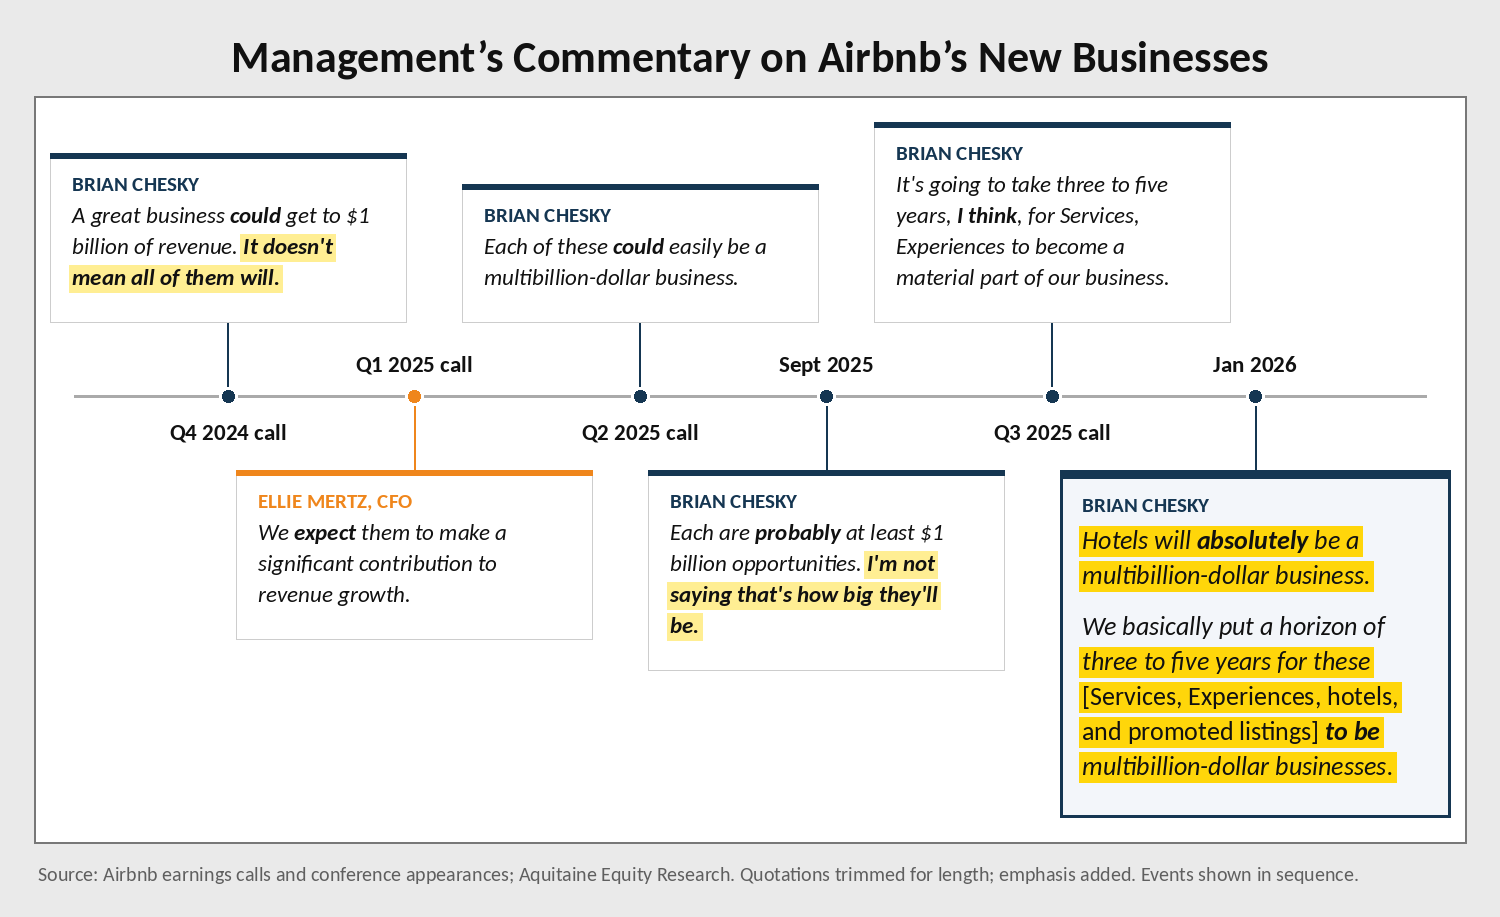
Still, the shift was easy to miss, for two reasons:
Chesky had given roughly a dozen interviews since Airbnb’s 2025 Summer Launch, making any one appearance easy to overlook.
No one expects a material departure from the official “script” on a daily tech news show.
Months later, the old framing was still circulating. On The Intrinsic Value Podcast, Daniel Mahncke said:
“Chesky has also said publicly that this Services marketplace alone could be around a billion dollars in annual revenue once it is fully rolled out…”
By then, as the timeline shows, Chesky had moved from describing a possible billion-dollar business to an expected multibillion-dollar one. And Services was the one he was most bullish on. After saying he was “really optimistic” that Experiences could become a multibillion-dollar business, he added: “I think Services is probably a significantly larger opportunity than Experiences…”
Airbnb was the podcast portfolio’s second-largest holding at the time (~11.5%). Accordingly, if a thoughtful, tuned-in investor like Mahncke was still working from the old assumptions, many others likely were too.
Even those who caught the remarks would likely have discounted them, if not dismissed them outright, given Chesky’s dated reputation for overhyping. As I argued at (probably too much) length in the deep dive, that was a mistake:
Airbnb had met or beaten consensus revenue and EBIT estimates in all but one quarter since going public. Therefore, to the extent Chesky had overhyped, it was rhetorical, not financial.
He had clearly learned from the experience. His communication had become noticeably more restrained in the years since.
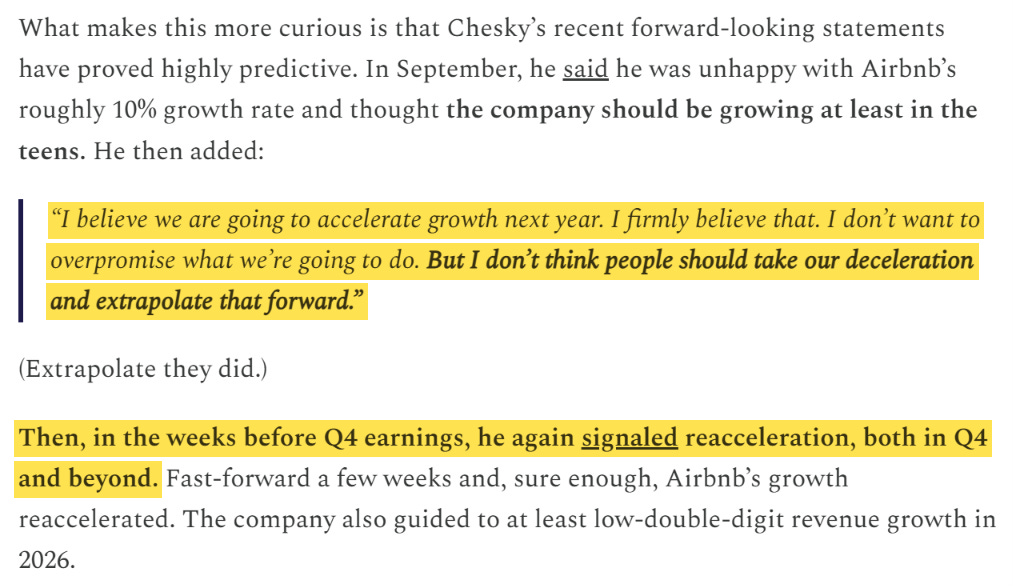
Most importantly, his recent forward-looking remarks had proved a reliable guide to subsequent results, as this excerpt from the deep dive shows:
Nor did the thesis require blind faith in Chesky. The assumptions were explicit and easy to stress-test, and the growth drivers spanned both the core business and the new offerings. Taken together, they made reacceleration not merely plausible, but the most likely outcome.
Not everyone saw it that way, of course. Take this argument about Experiences from an open letter to Chesky that circulated on X in 2025:
“Repeated Relaunches. The product [Experiences] was paused in 2023, reopened to new hosts only last September, and is being “relaunched” again this month. These resets are signals that the market, not the mechanics, is rejecting the idea.”
That logic would hold if Airbnb were simply trying the same thing again. It wasn’t. As I wrote last November, Chesky had already diagnosed what held back earlier versions: poor merchandising, limited visibility, and weak integration with social media, among other things. This time, there were convincing plans to fix each of them.
Visibility is the easiest to show. Compare the old homepage with the redesign:
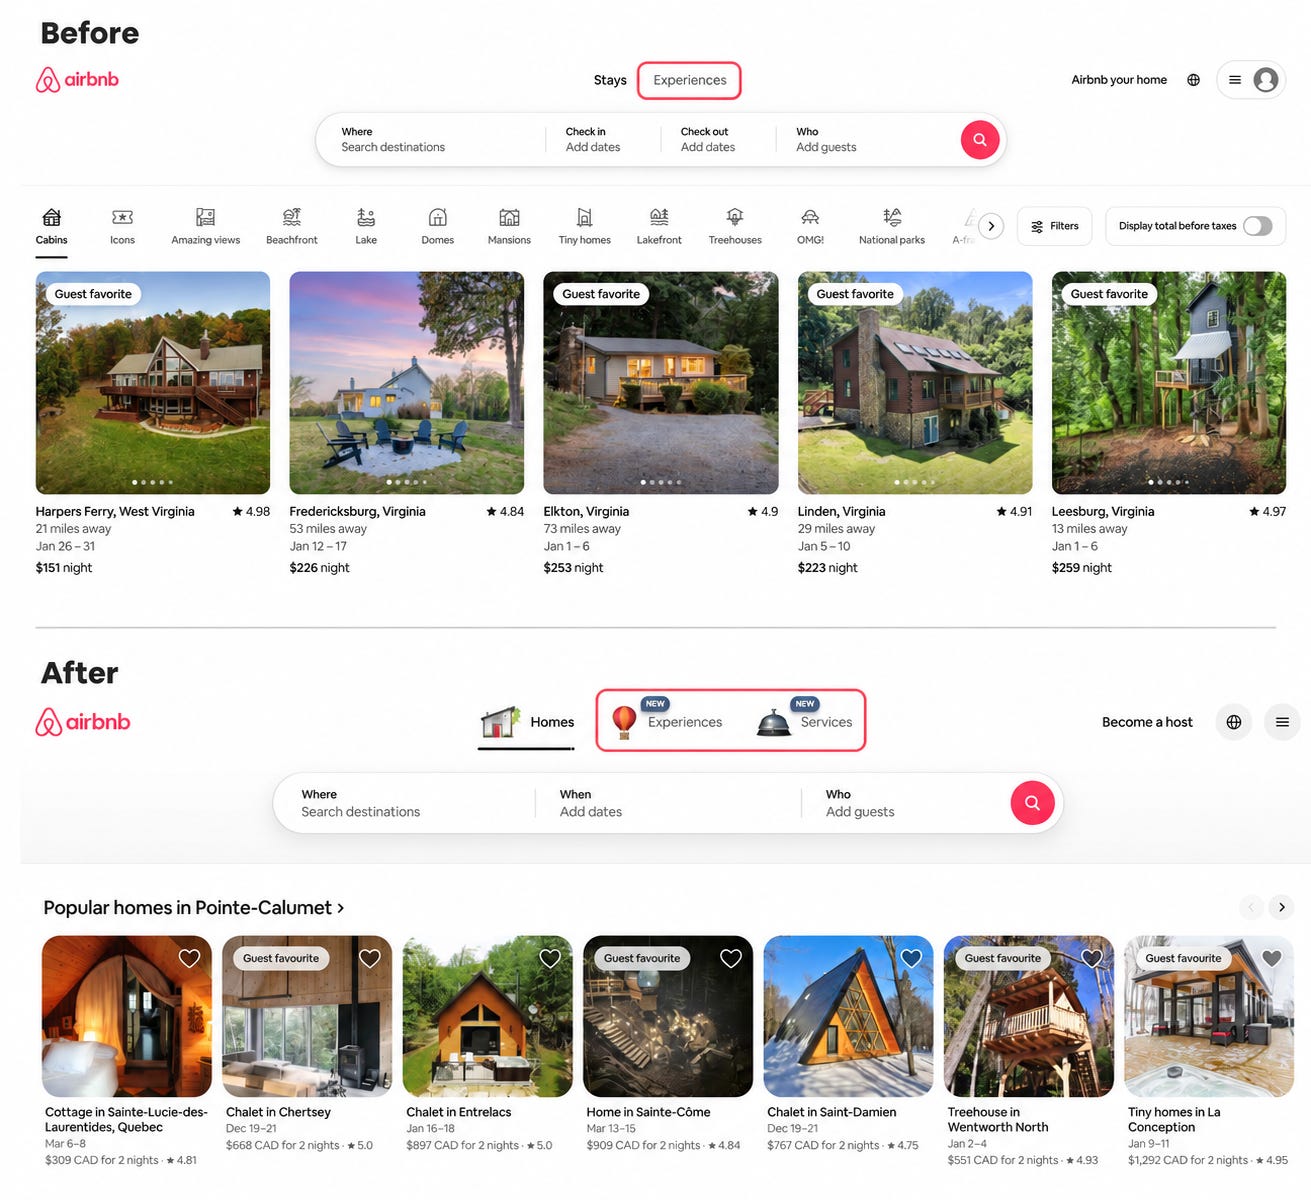
(Without the red box, you could be forgiven for missing Experiences in the old version entirely. The redesign makes it hard to miss, with animated icons that draw more attention than a still image conveys.)
That’s one fix of several, but you get the idea. Almost every bear argument I came across was similarly easy to poke holes in.
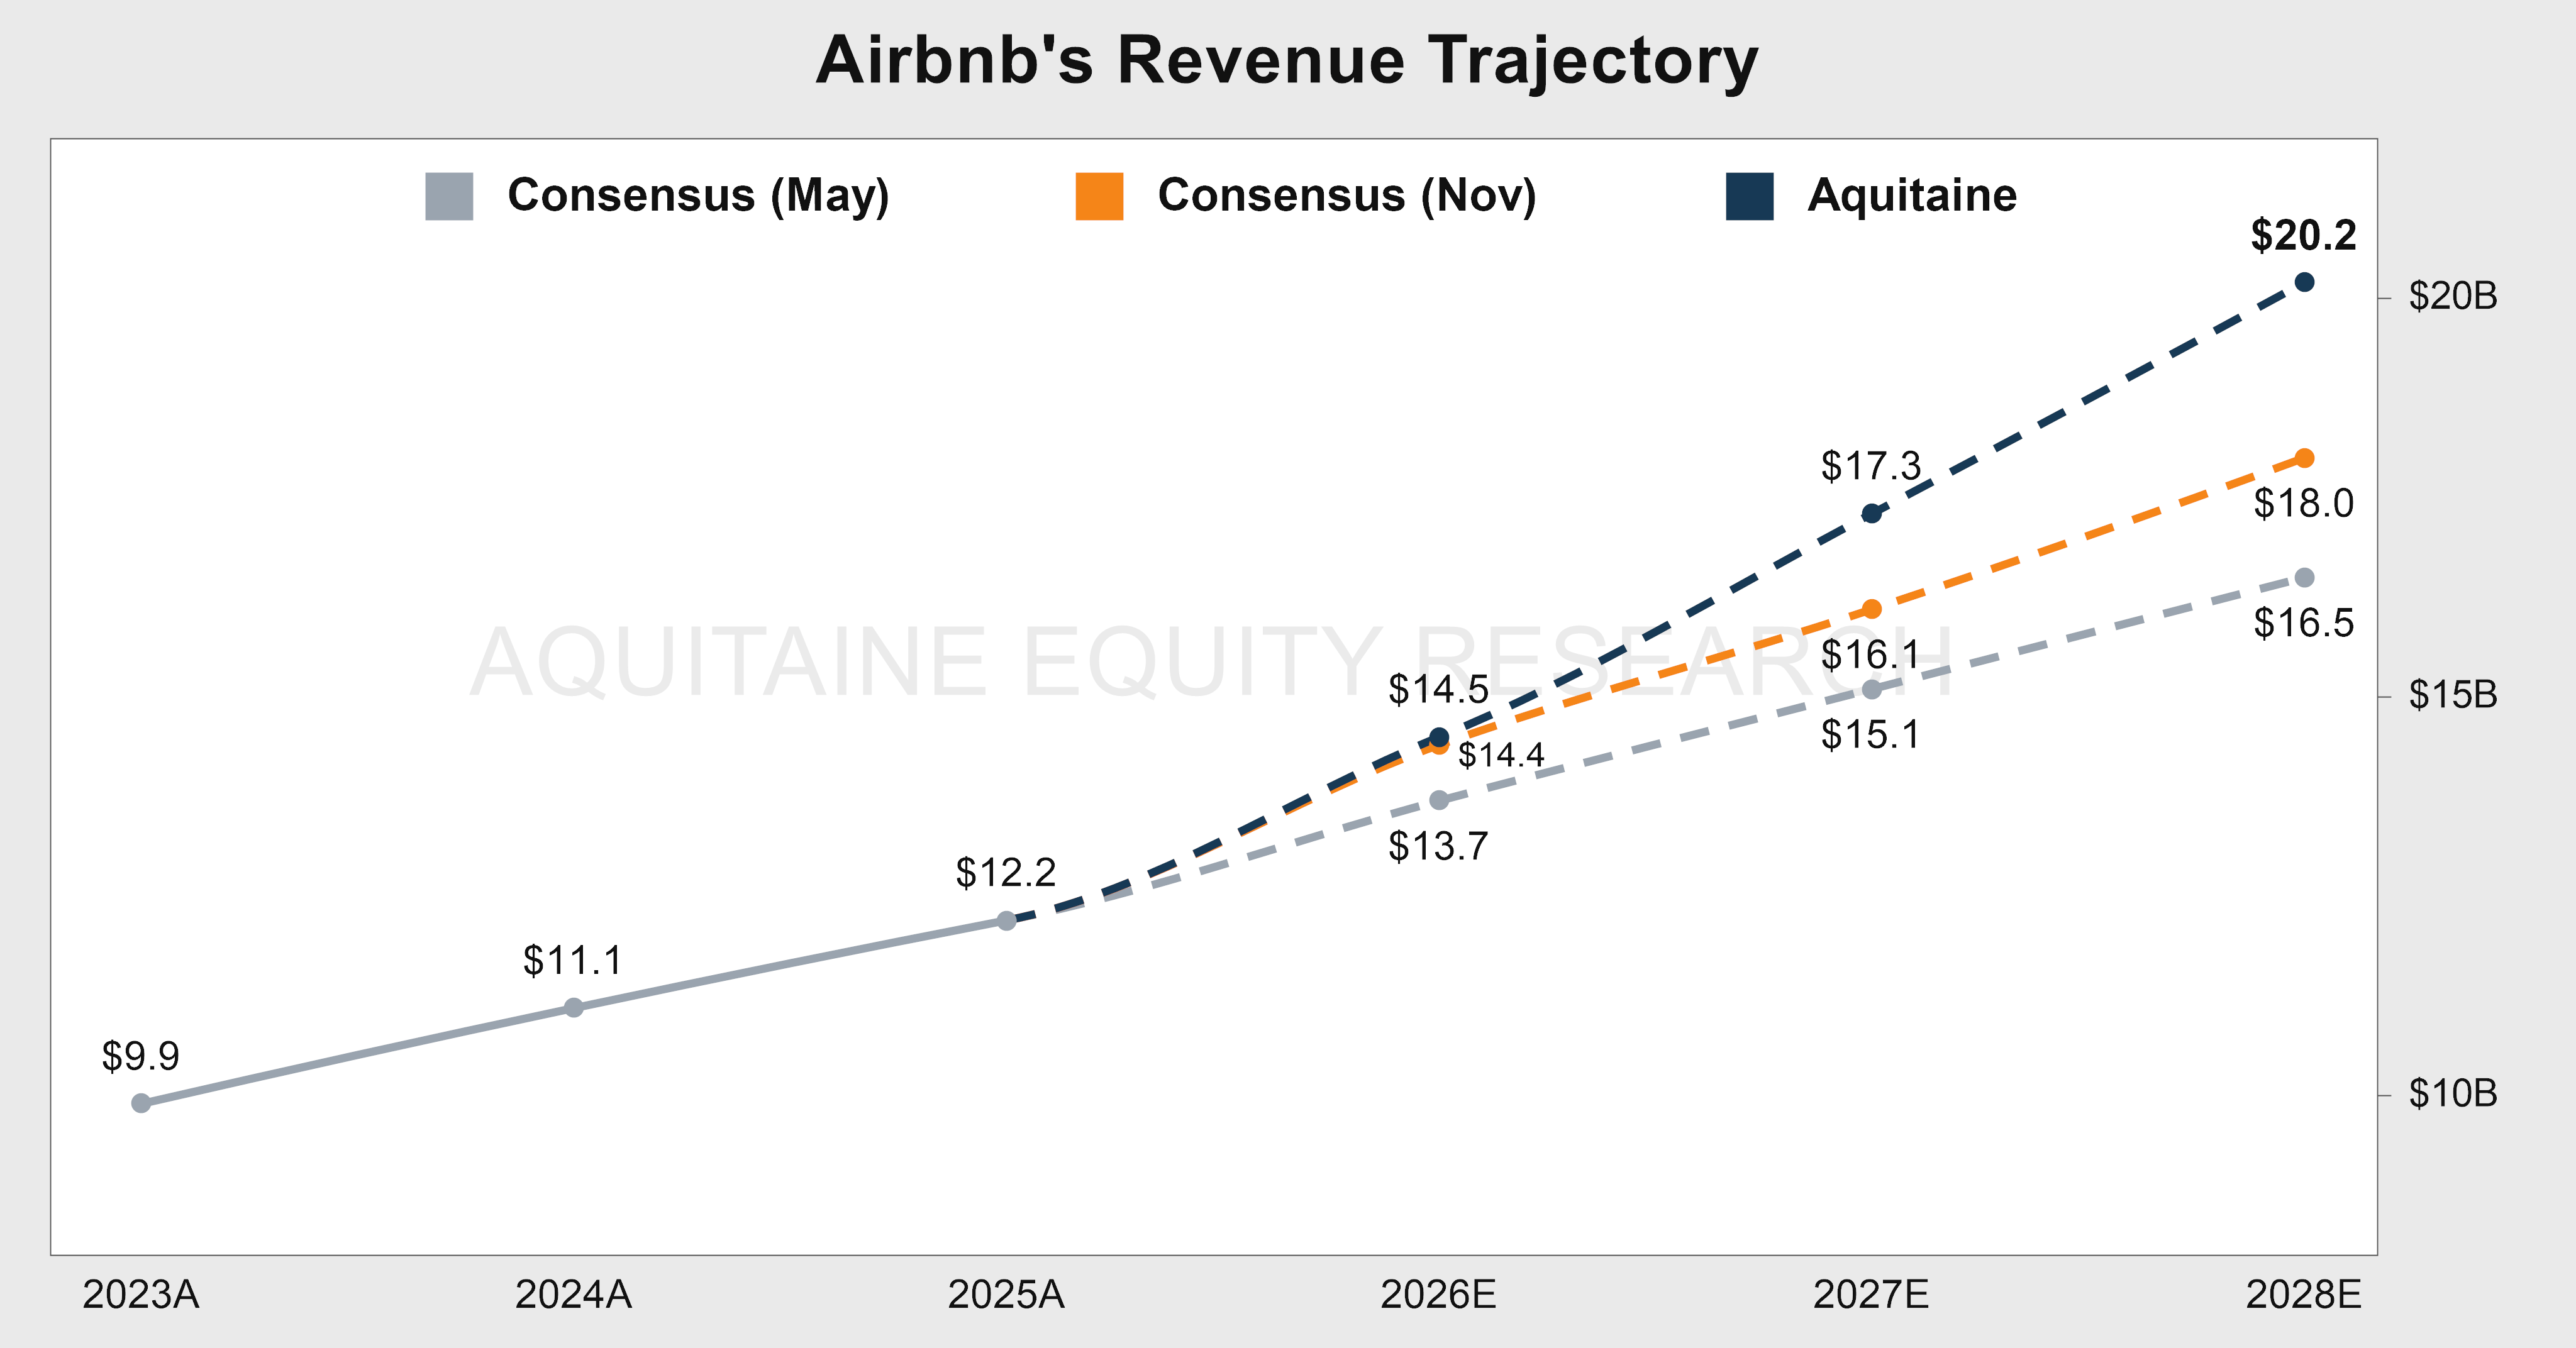
Either way, the reacceleration thesis is playing out, and consensus has risen considerably since May. For 2026, it has nearly caught up with my forecast from that time ($14.4B vs. $14.5B). Further out, a meaningful gap remains:
At ~$187 as of this writing, the stock is back in IPO-year territory, up ~56% YTD. That raises two questions: Can ABNB go higher from here? And is the risk-reward still attractive?
Let’s investigate.
Valuation
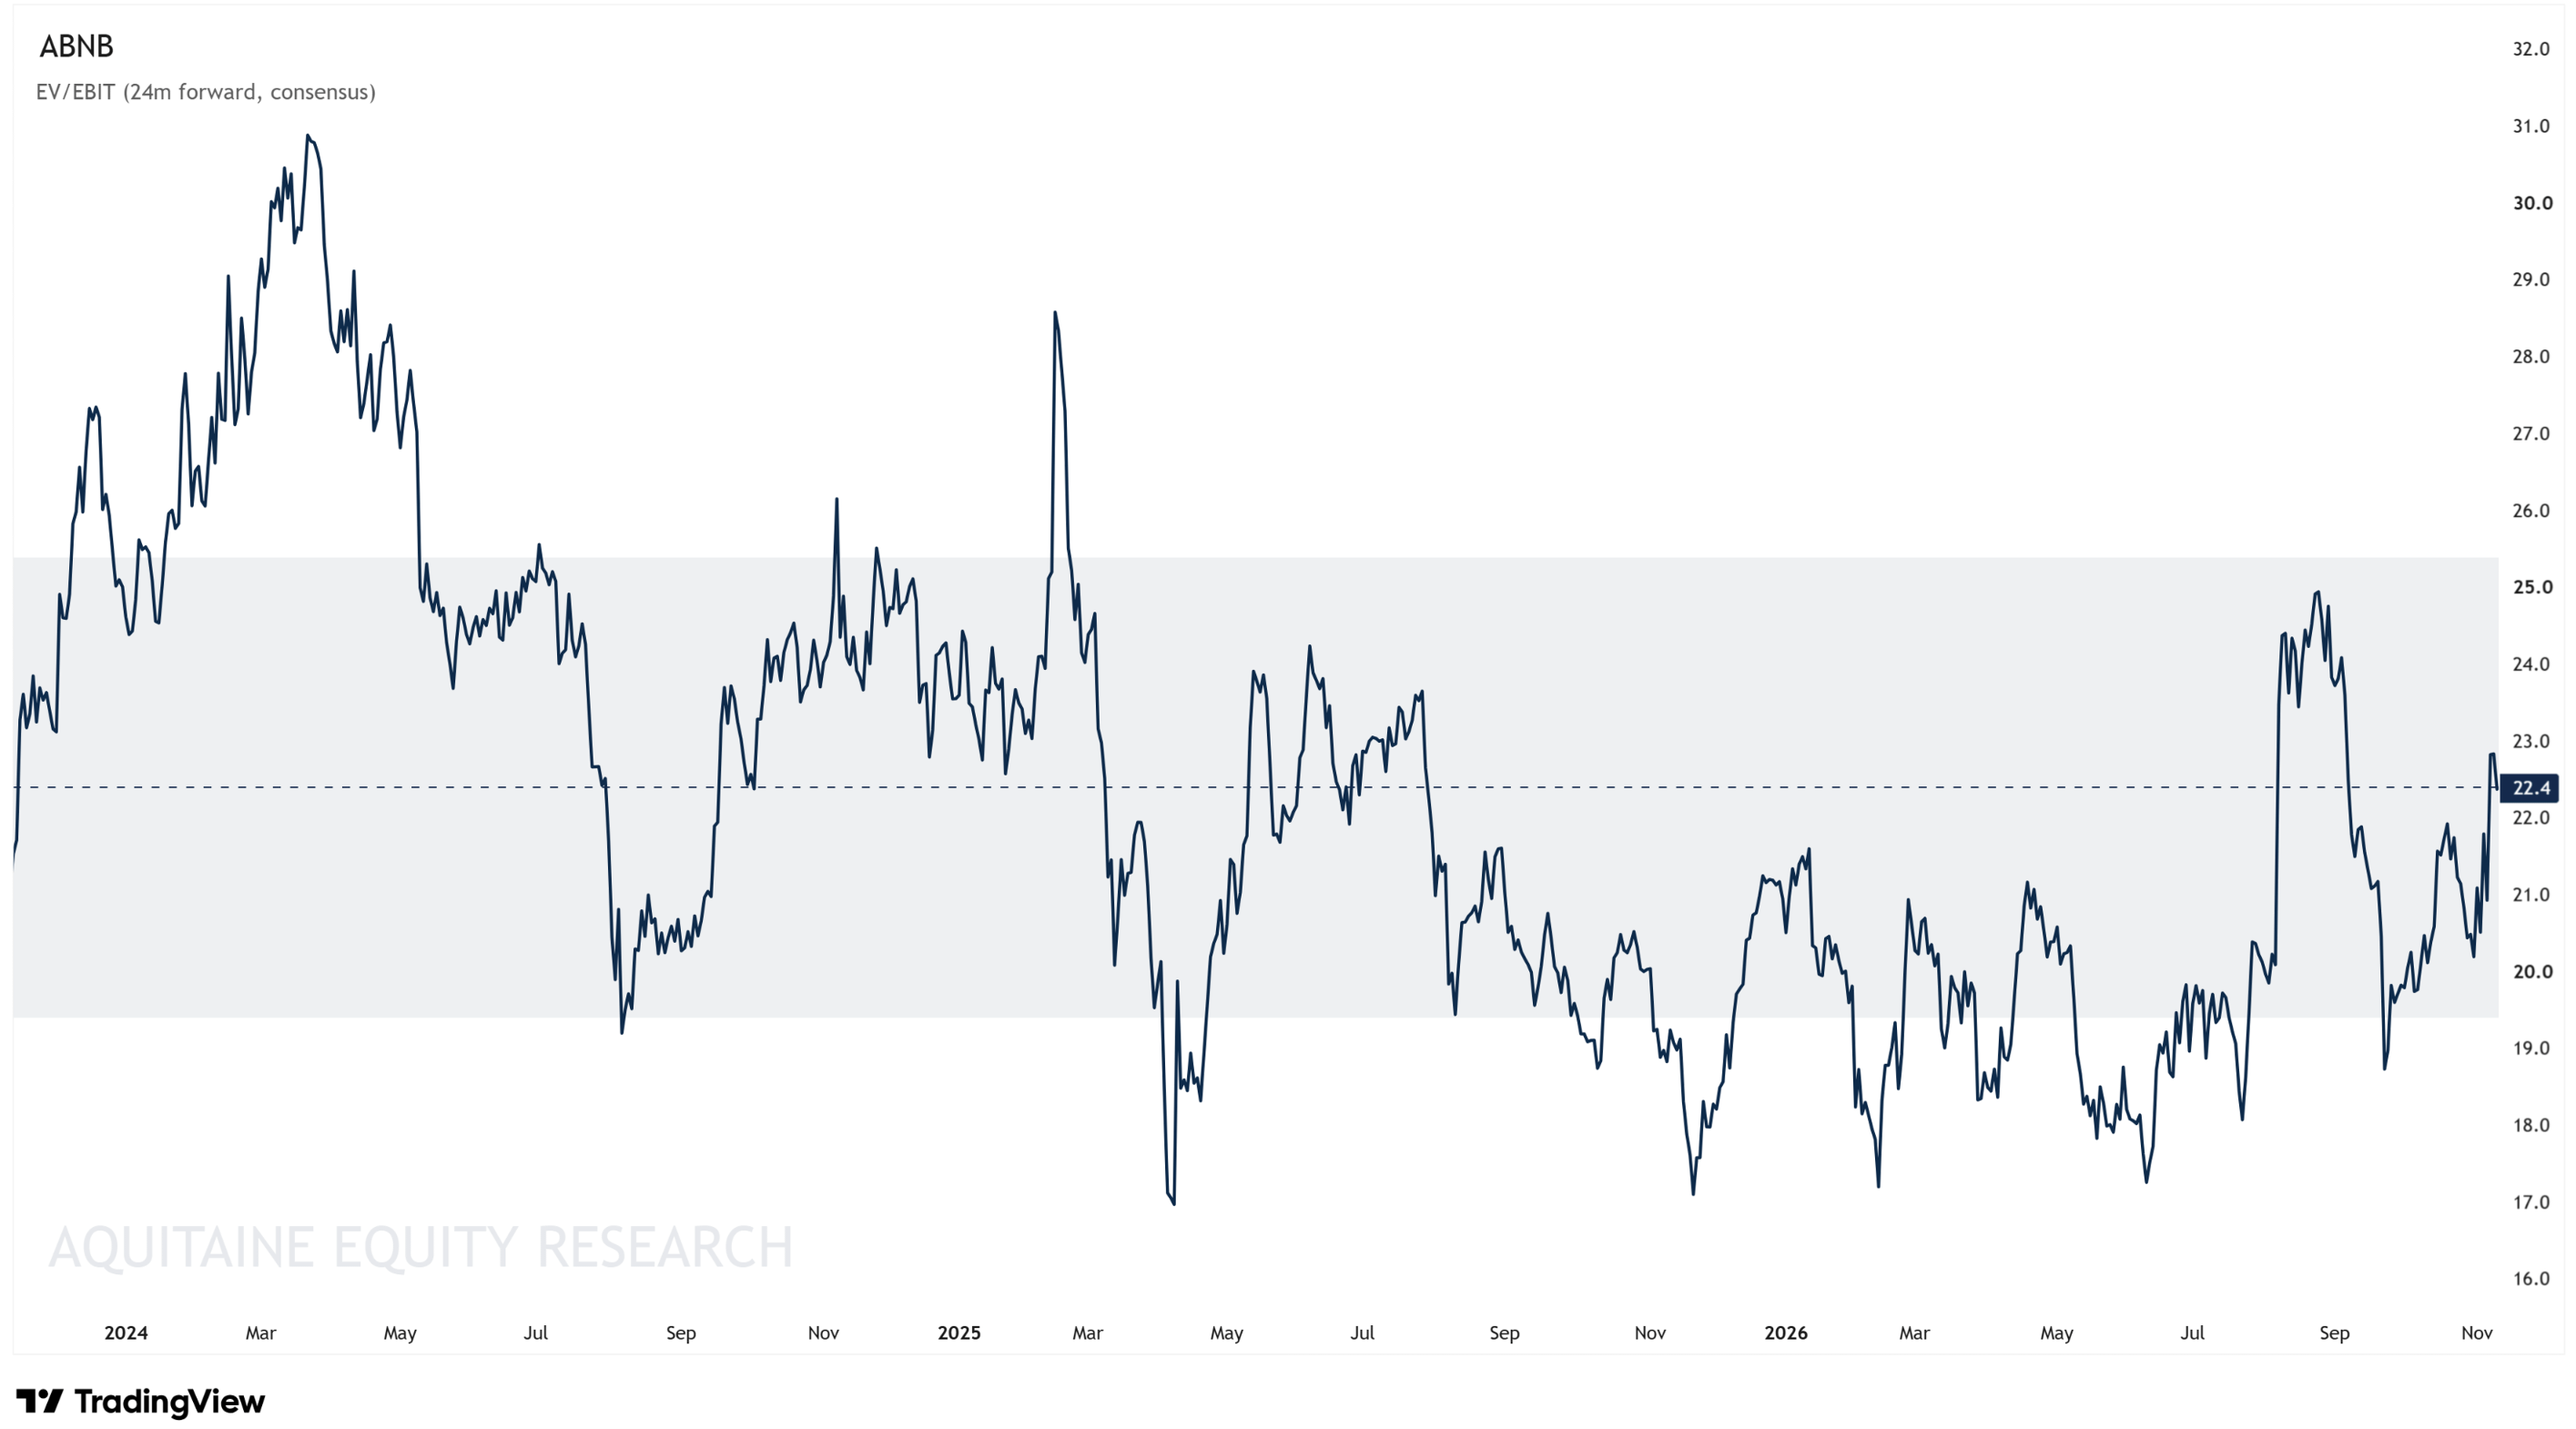
Even after the rally, ABNB remains within its historical range on a 24-month forward EV/EBIT basis using consensus estimates, sitting right on its three year average. On my forecasts, the multiple is lower. But that doesn’t necessarily make it a buy at these levels.